
For S-corporation owners, the 2025 tax year (and the returns you’ll file in 2026) brings more than just routine updates. Thanks in large part to the new “One Big Beautiful Bill Act” (OBBBA), the IRS has released significant changes to Form 1120-S Instructions.
At Galvin CPA & TAX, we’ve sifted through the updates to bring you the most critical changes affecting your S-corp’s deductions, reporting, and compliance.
Big Wins for Deductions & Credits
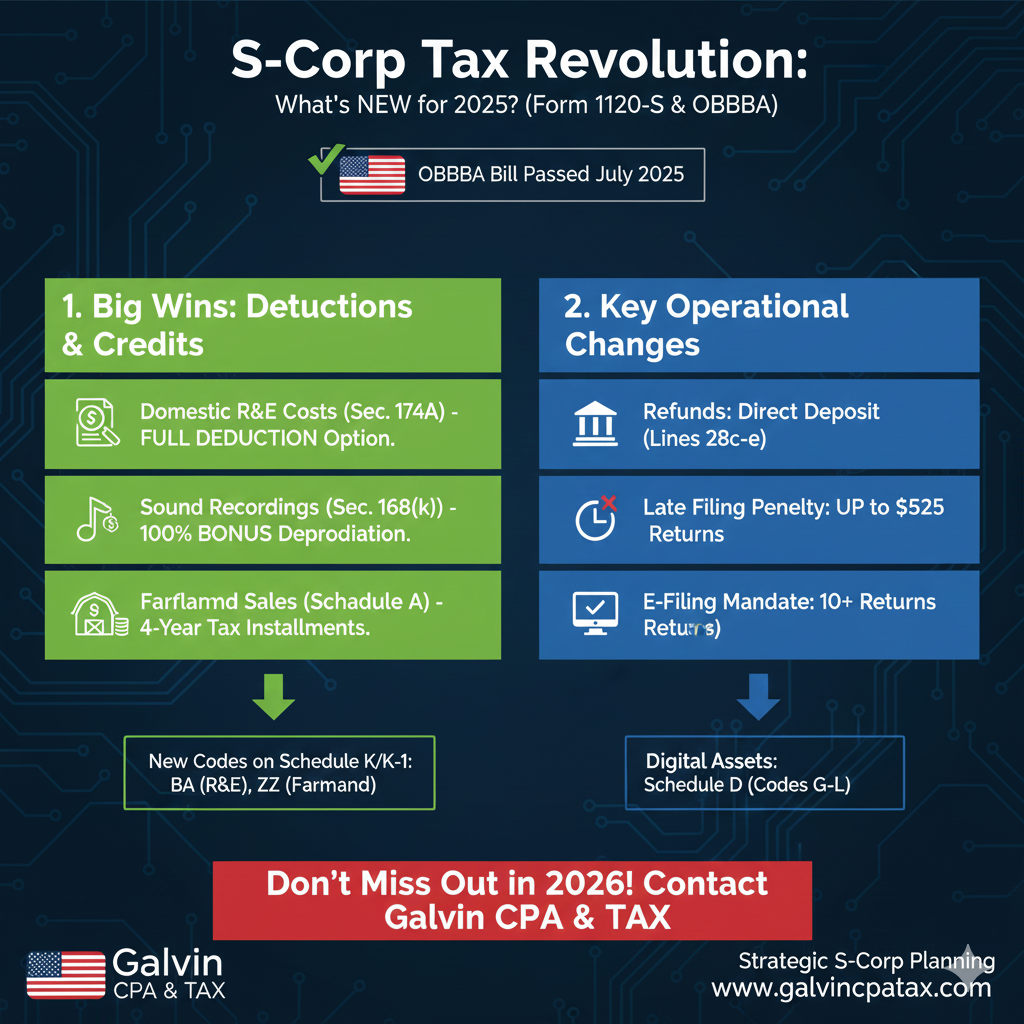
- Domestic Research & Experimental (R&E) Costs are Back! Under new Section 174A, S-corporations can now choose to fully deduct qualified domestic research and experimental expenditures in the year they are paid or incurred. This reverses a prior change that required capitalization, offering immediate cash flow benefits.
- Pro Tip: Your shareholders will see this reported with Code BA on Schedule K-1, Line 17d, which is important for any Section 59(e) elections.
- Sound Recording Productions Get a Boost: If your S-corp is involved in creating sound recordings, you may now be able to expense 100% of qualified costs under Section 181, or claim 100% bonus depreciation under Section 168(k) for productions commencing after July 4, 2025. This is a significant incentive for the music and audio industries.
- Flexible Tax Payments for Farmland Sales: Selling qualified farmland to a qualified farmer? A new provision allows S-corps to elect to pay the net income tax from these sales in four annual installments. This eases the tax burden and supports agricultural transitions.
- New Form: You’ll use a new Schedule A (Form 1062) for these transactions, reported with Code ZZ on Schedule K-1, Line 17d.
Key Operational & Reporting Enhancements
- Direct Deposit for Refunds: No more waiting for a paper check! Form 1120-S now includes Lines 28c, 28d, and 28e for direct deposit of any corporate refunds.
- Increased Late Filing Penalties: Stay on schedule! For returns filed in 2026, the minimum penalty for an S-corp return filed more than 60 days late has increased to the lesser of the tax due or $525.
- Electronic Filing Mandate Continues: If your business files 10 or more returns of any type, e-filing your Form 1120-S is mandatory.
- Digital Asset Reporting: The IRS is keeping pace with innovation. New reporting codes (G through L) have been added to Schedule D specifically for digital asset transactions (like cryptocurrency), ensuring clarity in reporting gains and losses.
Important Note on Conservation Contributions
The IRS has also tightened rules on qualified conservation contributions, preventing deductions if the contribution exceeds 2.5 times the sum of each member’s relevant basis. This aims to prevent abuse of syndicated conservation easements.
Don’t Get Caught Off Guard in 2026!
These updates can significantly impact your S-corp’s tax strategy and compliance. Missing new deduction opportunities or overlooking reporting changes can lead to missed savings or costly penalties.
Is your S-corporation prepared for the 2025 tax changes? Contact Galvin CPA & TAX today for a comprehensive review of your operations and tax planning to ensure full compliance and maximum savings.